How to Build a Saving Habit That Actually Sticks
More than 1 in 3 Americans can't cover a $400 emergency. Learn the behavioral science behind saving habits that stick, plus a step-by-step system to start with just $5.
Building a saving habit requires systems, not willpower. Research from University College London found that a simple daily behavior took a median of 66 days to become automatic, with individuals ranging from 18 to 254 days. Starting with as little as $5 per week, automating the transfer, and attaching the habit to an existing routine are the three core mechanics behavioral scientists consistently identify as most effective.
You have tried to save before. It lasted a week, maybe two. Then something came up. A bill, a birthday, a bad day that turned into a $40 DoorDash order. The savings plan quietly died, and you felt like a failure.
You are not a failure. The system is rigged against you.
Everything around you is engineered to make you spend. One-click buying. "Limited time" sales. Subscriptions that auto-renew while you sleep. Nobody taught you how to save, and that was not an accident. The economy runs on people who spend every dollar they earn. Saving was never part of the plan they had for you.
But here is what the system does not want you to know: saving is a skill. And like any skill, there is a method to building it. Behavioral scientists have spent decades figuring out exactly how habits form, stick, and become automatic. The research is clear. You do not need more willpower. You need a better system.
This article gives you that system.
Building a saving habit is not about willpower. It is about systems. According to the Federal Reserve, more than one in three American adults could not cover a $400 emergency expense with cash. The fix is not earning more. It is starting ridiculously small ($5/week), automating the transfer, and stacking the habit onto something you already do. Small, automatic, consistent. That is the formula.
Read more: Small Steps, Real Results
Why Do Most Saving Attempts Fail?
According to the Federal Reserve's Survey of Household Economics and Decisionmaking, fielded in October 2025, 63% of adults said they could cover a $400 emergency expense using cash or its equivalent. Flip that around: more than one in three could not, and the figure has not budged in four years. That is not because Americans are lazy. It is because the default setting in this economy is "spend everything."
Most people fail at saving for three reasons. They start too big. They rely on willpower. And they treat saving as punishment instead of progress. Each failure has a specific fix:
| Why it fails | What it looks like | The fix |
|---|---|---|
| You start too big | "$500 a month starting Monday" | Start at $5 a week. It should feel almost pointless. |
| You rely on willpower | Manually moving money when you remember | Automate the transfer on payday so no decision is required. |
| You treat it as punishment | Saving feels like losing something | Track the streak, not the balance, so progress is visible early. |
| You save into the wrong account | Cash sitting next to your spending money | Separate account, different bank, slightly annoying to reach. |
If your first savings goal is $500 a month, you have already lost. That is not a habit. That is a lifestyle overhaul. And lifestyle overhauls do not stick.
66 days
Median time for a daily behavior to become automatic (range: 18 to 254 days)
Lally et al., European Journal of Social Psychology, 2009
A 2009 study by Philippa Lally at University College London followed 96 volunteers who repeated one eating, drinking, or exercise behavior every day in the same setting. The behavior took a median of 66 days to become automatic, with individuals ranging from 18 to 254 days. Doing it consistently mattered, and missing a single day did not derail the process.
The takeaway: start so small it feels almost pointless. That is the point.
A study published in the European Journal of Social Psychology (Lally et al., 2009) found that a daily behavior took a median of 66 days to become automatic, and that missing a single day did not derail the process. Applied to saving, this means a $5/week automatic transfer is more likely to become permanent than an ambitious $500/month plan that collapses after two weeks.
Read more: Nobody Taught You This
What Does Behavioral Science Say About Building Habits?
Behavioral researchers like James Clear (author of Atomic Habits) and BJ Fogg (Stanford's Tiny Habits) agree on the core mechanics. According to Clear, habits form through a four-step loop: cue, craving, response, reward. The trick is not to push harder. The trick is to make the habit easy.
Here are the five principles that make saving stick.
1. Start ridiculously small
BJ Fogg's research at Stanford shows that the best way to build a habit is to make it so small you cannot say no. His term is "Tiny Habits." For saving, that means $5 a week. Not $50. Not $200. Five dollars. The amount does not matter yet. The repetition does.
2. Automate it
Willpower is a limited resource. Behavioral economist Richard Thaler won a Nobel Prize partly for his work on "nudge" theory, showing that people make better financial decisions when the default is set for them. Set up an automatic transfer from your checking account to a separate savings account. Make it happen on payday. Now saving is the default, and spending requires effort.
3. Stack it onto an existing habit
James Clear calls this "habit stacking." You attach the new habit to something you already do every day. For example: "After I get my paycheck notification, I check my savings balance." Or: "After I make my morning coffee, I open my savings app for 10 seconds." The existing habit becomes the trigger for the new one.
4. Make it visible
Progress you can see is progress you keep. You need to see the number going up. Check your balance once a week. Screenshot it. Write it on a sticky note. Whatever makes the growth feel real.
There is a reason old-school bank passbooks worked so well. Every deposit got a physical stamp. You could flip through the pages and watch your savings grow with your own eyes. Digital savings lacks that tactile feedback. Finding a way to make your progress visible, even if it is just a simple spreadsheet, changes everything.
5. Celebrate small wins
Fogg's research emphasizes that positive emotion is what locks in a habit. When your automatic transfer hits, say "nice" out loud. When you hit $100 saved, do something small to mark it. Your brain needs to associate saving with feeling good, not with deprivation.
Behavioral economist Richard Thaler's Nobel Prize-winning research on "nudge" theory demonstrates that setting beneficial defaults dramatically improves financial outcomes. When saving is automatic and spending requires active effort, people save more consistently, a principle now built into 401(k) auto-enrollment. In a National Bureau of Economic Research study of three large employers (Choi, Laibson, Madrian and Metrick, 2001), 401(k) participation exceeded 85% at all three once enrollment was automatic.
Read more: Small Steps, Real Results
Where Do You Find the Money?
You do not need a raise. You probably do not even need to cut anything painful. You just need to look at where your money is already going.
Make coffee at home three days a week instead of buying it. Save $15 a week. Bring lunch to work twice a week instead of eating out. Save $18 a week. Cancel one streaming service you have not watched in a month. Save $15 a month. That is about $42 a week you just freed up, and you barely changed your routine.
Here is the math on common spending swaps:
| Swap | Weekly Savings | Monthly Savings | Annual Savings |
|---|---|---|---|
| Make coffee at home 3x/week | $15 | $65 | $780 |
| Bring lunch 2x/week | $18 | $78 | $936 |
| Cancel 1 unused streaming service | $3.50 | $15 | $180 |
| Skip impulse Amazon buy (1x/month) | $6 | $25 | $300 |
| Total | $42 | $183 | $2,196 |
That $42 a week, invested consistently at an average 8% return, becomes about $33,000 in 10 years (weekly deposits, each growing at the stated annual rate). That is money you were already losing to the cost of financial ignorance. At 10%, it is closer to $36,500. You did not earn more money. You just stopped lighting it on fire.
And here is the thing. You will not miss most of it. The coffee you made at home? It is fine. The lunch you brought? Also fine. The streaming service? You already forgot it existed.
Related: You're Already Wasting Money | The Subscription Trap | The Latte Factor
How Do You Build the System Step by Step?
Here is the actual playbook. Five steps. Each one takes less than 10 minutes.
Step 1: Open a separate savings account
Do not save into your checking account. You will spend it. Open a free high-yield savings account at an online bank. As of October 10, 2026, the best advertised rate on Bankrate's list was 4.27% APY, while big online banks such as Ally paid closer to 3.10%. Either beats the 0.37% national average by a mile. The separation creates a mental boundary between "money I spend" and "money I am building."
Step 2: Set up an automatic transfer for $5
Not $50. Not $100. Five dollars. Set it to transfer automatically on your payday. You will not notice $5 leaving your checking account. That is the entire point. If $5 feels too easy after a month, bump it to $10. The ramp-up happens naturally.
Step 3: Stack the habit
Pick an existing daily routine and attach your saving awareness to it. "After I pour my morning coffee, I glance at my savings balance." You are not doing anything complicated. You are just keeping the habit visible.
Step 4: Track your streak
Mark a calendar. Use an app. Keep a running note on your phone. Every week the automatic transfer hits, that is a win. When researchers tested 54 different programs to get 61,293 gym members exercising more (Milkman et al., Nature, 2021), the top performer paid small rewards for coming back after a missed workout. The lesson for saving: plan for the missed week, then restart the chain.
The next step is worth more than it looks. Raising the amount you put in beats chasing a better return, and it is the one lever you actually control:
Saving More Beats Earning More
Same 30 years. Doubling the contribution adds $101,500; a three-point better return adds $77,700.
Model: equal weekly contributions for 30 years, balance growing at the stated annual rate. 7% and 10% approximate the S&P 500's long-run averages after and before inflation (NYU Stern, 1928 to 2025).
Step 5: Increase when life gives you a window
Got a tax refund? Drop a portion into savings. Paid off a bill? Redirect that monthly payment. Got a raise? Increase your automatic transfer by $5 before you adjust your lifestyle. These "found money" moments are the fastest way to accelerate without feeling any pain.
Most financial advice tells you to budget, then save what is left over. That is backwards. The people who actually build wealth save first and spend what is left over. It is the same money. It is the same paycheck. The only difference is the order of operations. Pay yourself first, even if "paying yourself" is $5 a week.
Ready to build a habit that actually sticks?
Learn the system for turning small actions into lasting wealth.
Where Should Your Savings Go?
Once you have the habit locked in and your balance starts growing, you will want your money working harder than a savings account. Here are your main options.
A high-yield savings account is the right home for your emergency fund, and that article walks through how many months of expenses your own situation actually calls for. It is safe and liquid. The best advertised accounts paid about 4.27% APY in October 2026 (Bankrate), big online banks closer to 3.10%, against a 0.37% national average (FDIC, September 2026). But after 3.4% inflation, the twelve month rise in consumer prices through August 2026 reported by the Bureau of Labor Statistics, and taxes, even the best rate barely breaks even, and the big-bank rate falls behind. It preserves money. It does not grow it.
Index funds like the S&P 500 have returned roughly 10% annually since 1928, according to NYU Stern: $100 invested at the start of 1928 was worth $1,157,598.95 by the end of 2025, a 10.02% geometric return across 98 years. These are for money you will not touch for 5 to 10 years or more. Set up a recurring buy at a brokerage. No stock picking. No guessing.
The Compound Growth Curve: Coffee + Lunch Savings Invested at 8%
$4,165 a year ($80 a week) redirected from coffee and lunch, invested weekly. Most of the final balance is growth, not deposits.
Untaught calculation, weekly deposits compounding at an assumed 8% a year (below the S&P 500's 10% average since 1928, NYU Stern). Not a guarantee.
Bitcoin is another option for a portion of your savings. It is available 24/7, has no minimum purchase amount, and its fixed supply of 21 million coins means no government can print more. It is more volatile than index funds, so it is not for your emergency fund. But as a long-term allocation alongside other investments, it is worth considering.
The vehicle matters less than the habit. A person who saves $10 a week into a plain savings account for 20 years is in dramatically better shape than someone who "plans to invest" $500 a month but never starts. The "I'll start tomorrow" trap destroys more wealth than any bad investment.
That ordering is not a throwaway line, and it is the opposite of how most people approach this. The usual instinct is to research the perfect account, the perfect fund, and the perfect allocation before moving a single dollar, which means months pass with nothing saved. The habit is the part that compounds. The vehicle is a setting you can change in ten minutes, any time, for the rest of your life.
So pick the boring option today and upgrade it later. A high-yield savings account you actually fund beats a brilliant portfolio you never open.
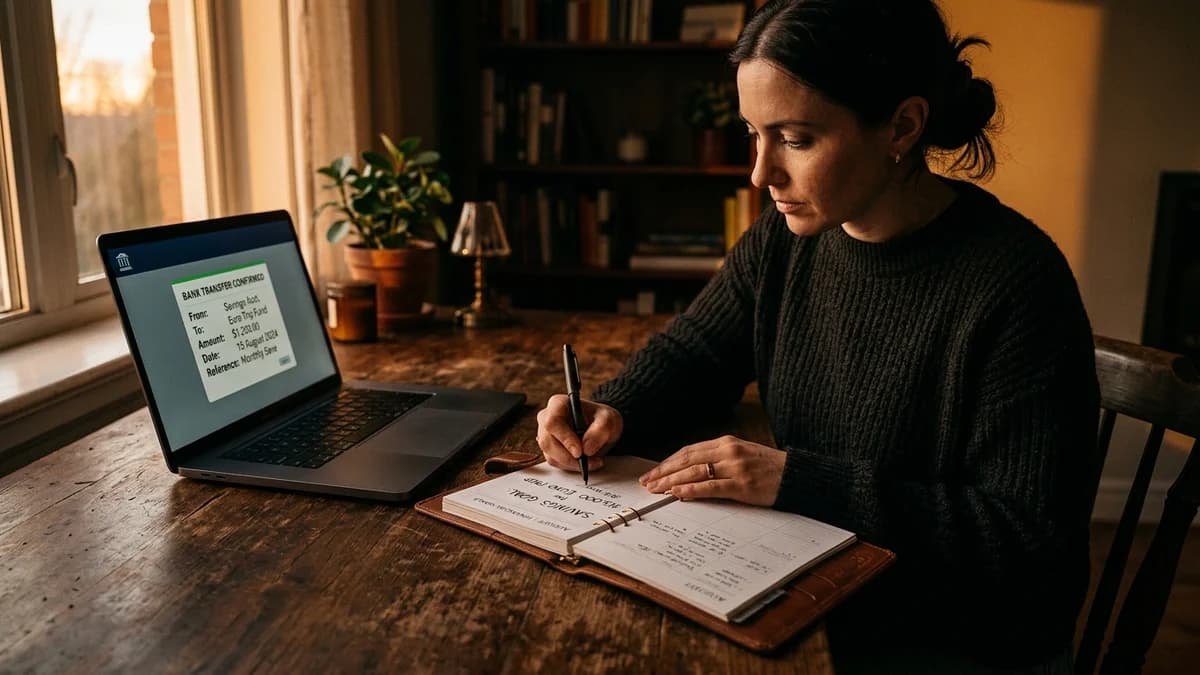
In practice that first upgrade looks less like a strategy session and more like ten minutes with a planner and a transfer screen open side by side.
Related: How to Start Investing With No Money | What Is Dollar Cost Averaging? | $20 a Week for 10 Years
Frequently Asked Questions
The questions below come up the most from people who are actually trying this, not theorizing about it. If you're stuck figuring out where to start, the amount to save, or how to keep going when motivation dips, the answers here are the ones we rely on.
Nothing below is clever. It's just what works when you strip the financial guru content down to basics.
Start with $5 a week. Philippa Lally's habit formation research (European Journal of Social Psychology, 2009) found that repeating the same small action in the same setting is what makes it automatic. Five dollars a week for a year is $260. That is not life-changing money. But the habit you build in those 12 months is. Increase gradually as saving starts to feel automatic.
You did not fail because of a character flaw. You failed because you were using willpower instead of systems. Automate the transfer. Make it small. Attach it to an existing routine. Remove the decision from the equation.
If you have high-interest debt (20%+ credit card APR), focus most of your effort there. No savings account or investment reliably returns 20%. But even then, save something. Even $5 a week. Keeping the habit alive matters more than the dollar amount. Once the debt is gone, you already have the saving muscle built.
A savings account is a great first step, but it will not build wealth. The 0.37% national average savings rate (FDIC, September 2026) loses purchasing power against 3.4% inflation (BLS, twelve months through August 2026). Once you have an emergency fund, move your savings habit into investments. A $20/week DCA into an S&P 500 index fund grows to roughly $17,400 in 10 years at historical average returns.
The Habit Is the Foundation
Saving is not a math problem. If it were, everyone would do it. It is a behavior problem. And the solution is not discipline. It is design.
Design your environment so saving happens automatically. Start with $5. Automate it. Stack it onto something you already do. Track the streak. Celebrate the wins. Then slowly increase. Before you realize what happened, you will have built something real.
And once you have the habit locked in, something bigger opens up. That money you are setting aside can start working for you. It can compound. It can grow. $20 a week for 10 years becomes about $17,400 in an index fund. Give it 30 years and it reaches roughly $179,300.
Here is the whole system on one page, in the order you actually do it:
| Week | What you do | Why it works |
|---|---|---|
| Week 1 | Open a separate high-yield account | Distance from your spending money is the entire point |
| Week 1 | Automate $5 on payday | Removes the decision, which is where willpower fails |
| Weeks 2 to 9 | Do nothing, let it run | Lally's 66 days is the window where it becomes automatic |
| Week 10 | Check the streak, not the balance | $50 is not impressive. Ten for ten is. |
| Any raise or windfall | Add $5 to the transfer | Escalate before lifestyle absorbs it |
| Once the cushion is full | Redirect the habit into investing | Same habit, better vehicle |
You are not just building a savings account. You are fighting back against a system that was designed to drain your purchasing power while you were not paying attention. Every dollar you save is a dollar the system did not get.
Open a free high-yield savings account today. Set up a $5 automatic weekly transfer. Stack the habit onto your morning routine. That is the entire system. Start this week.
Start with $5. Start this week. The habit is the hardest part, and it is also the only part that matters.
This article is part of the Small Steps, Real Results series, which breaks down how ordinary people can build real wealth with small, consistent actions. No jargon. No gatekeeping. Just the science and the steps.
This article is for educational purposes only and does not constitute financial advice. Untaught does not hold, move, or custody any funds. Past performance does not guarantee future results. Always do your own research before making investment decisions.
Quick calculator
Your coffee money could have become
$19,233
from $9,900 invested
Monthly buys, Oct 2021 to Sep 2026, at Coin Metrics month-end closes. Past results, not a forecast.